RyRo Loan Centre

Construction loan broker, Sydney

Construction Loans in Sydney: Built Around Your Build

Building a new home, doing a knock-down rebuild or working through a land and construction package? RyRo Loan Centre arranges construction loan finance from 50+ lenders and manages the process from pre-approval through to your final progress payment.

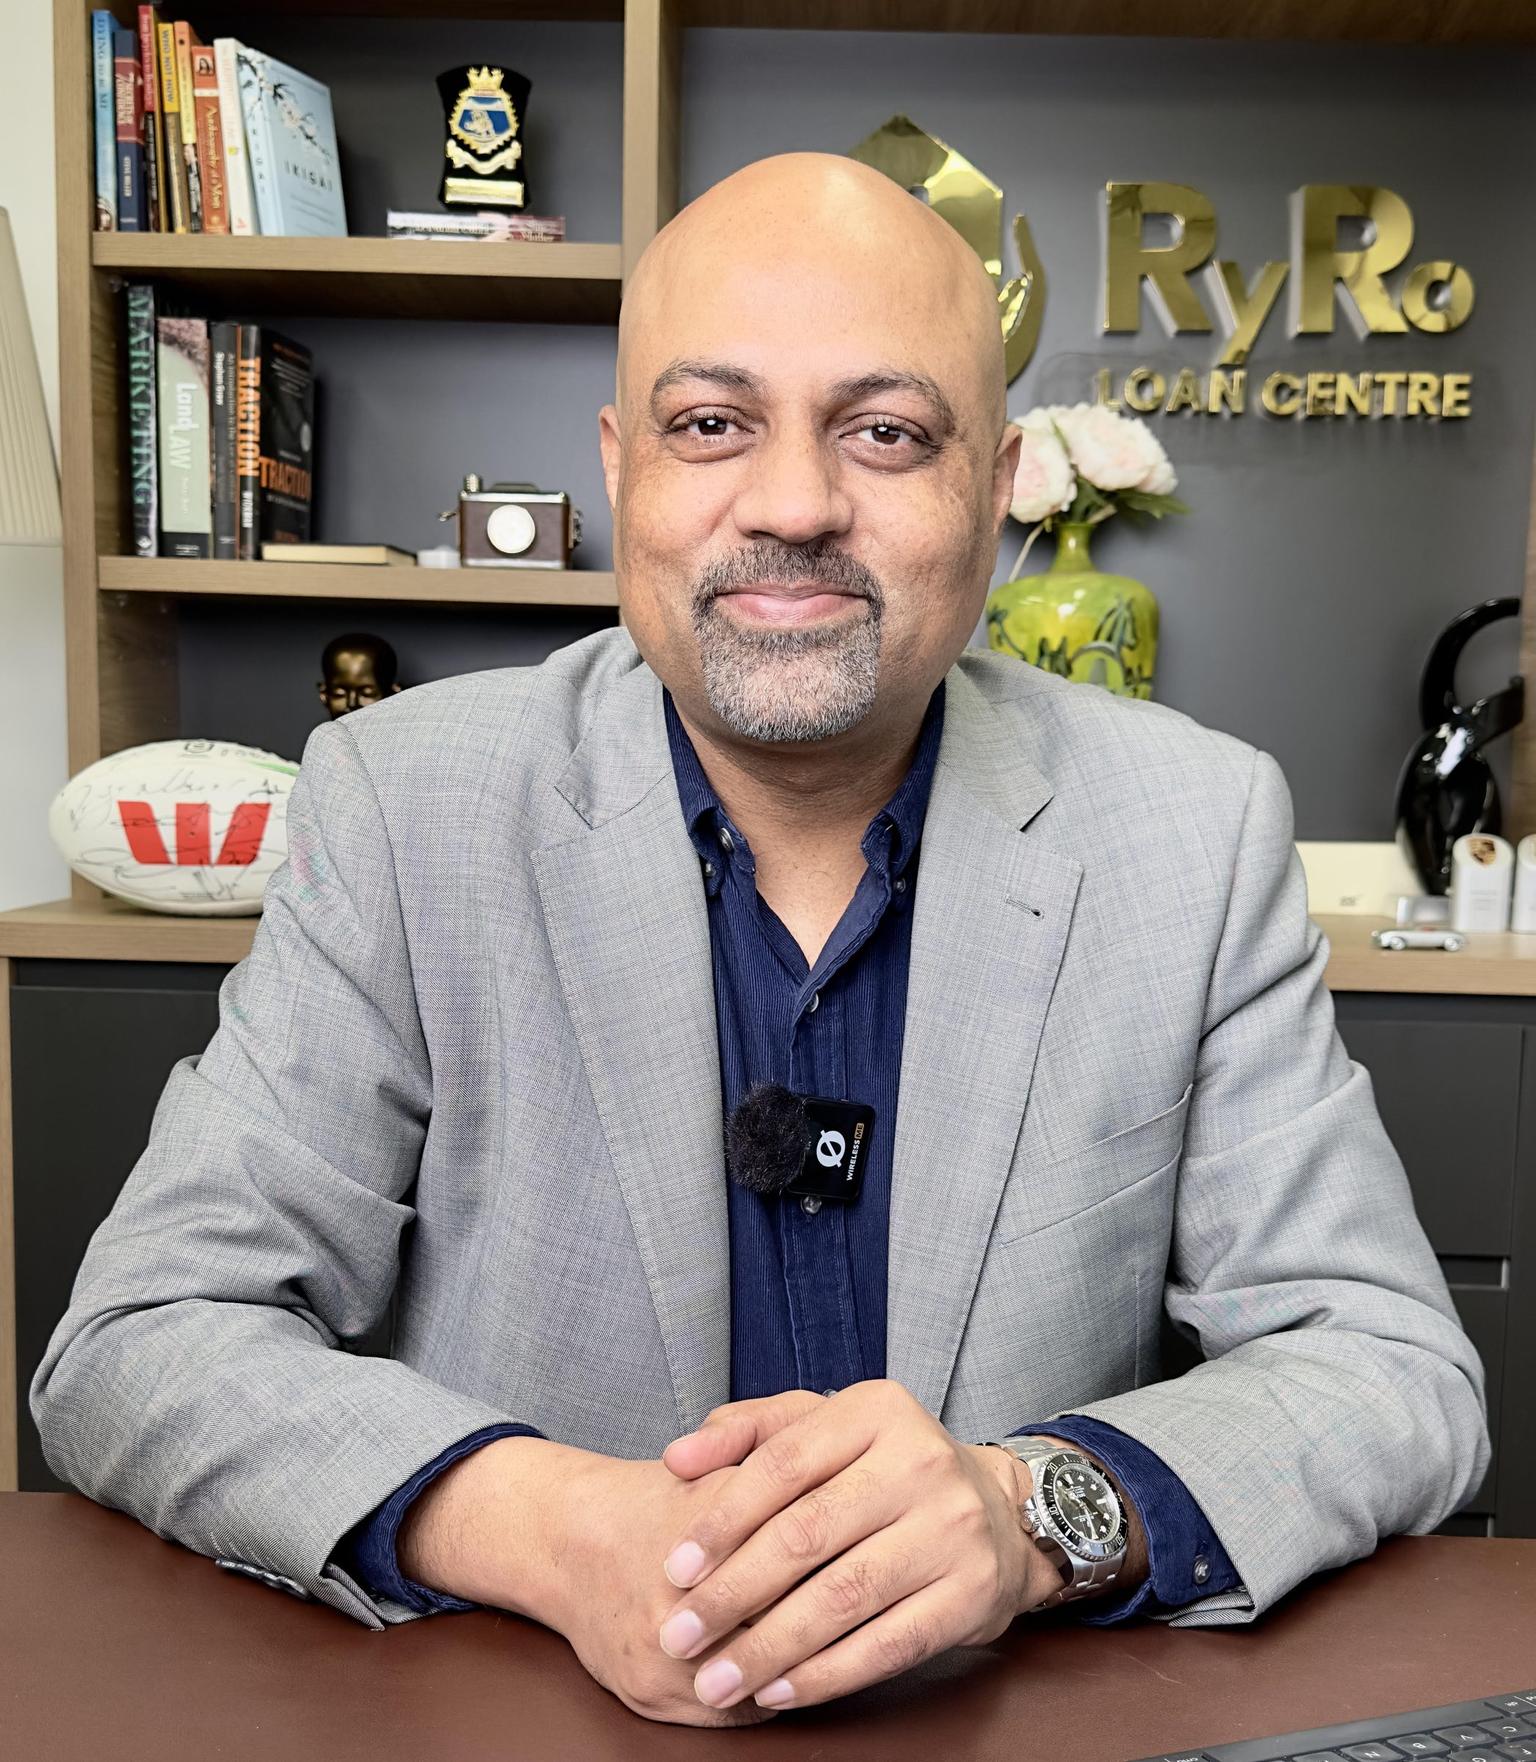
Sumit Joshi, principal broker at RyRo Loan Centre

Talk to a Construction Loan Broker Today

Tell us about your build. We'll match you with the right lender.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews
  • New builds, knockdown rebuilds and owner builder projects
  • We manage every progress payment with your lender
  • Based in Norwest, Sydney. $0 broker fees
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Commonwealth Bank Elite Broker FY23-24 badge
  • Westpac Gold Broker badge
  • ANZ Premium Broker badge
  • NAB Premium Broker badge
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge

Updated November 2026

Understanding

What Is a Construction Loan?

A construction loan (also called a building loan) is a type of home loan specifically designed to fund the construction of a new residential property. Unlike a standard home loan where the full amount is advanced upfront, a construction loan releases funds progressively, in stages, as each phase of the build is completed. This structure means you only pay interest on the amount that has been drawn down at any point, not on the full loan balance.

During the construction period, most lenders offer interest-only repayments. Once the build is complete, the loan converts to a standard home loan with principal and interest repayments. Construction loans are used for new house builds on vacant land, house and land packages, knock-down rebuilds on established blocks, dual occupancy and duplex builds, and major structural renovations (generally above $50,000).

  • The loan is structured around your fixed-price building contract
  • Funds go to your builder at each agreed milestone: slab, frame, lock-up, fix-out and completion
  • Based in Norwest, we help owner-occupiers, first home buyers and investors finance new builds across Sydney, NSW and Australia

Not sure what you can spend on the build? Start with the borrowing power calculator, or ask us to work it out against your builder's quote.

Quick answer

Who arranges construction loans in Sydney?

RyRo Loan Centre arranges construction loans in Sydney for people building a new home, doing a knockdown rebuild or buying a house and land package. A construction loan pays your builder in stages as the build progresses, and you pay interest only on the amount drawn so far. RyRo compares construction lenders, sets up the progress payment schedule and manages each drawdown from its Norwest office in the Hills District, and is rated 5.0 from 360+ Google reviews.

50+
Lenders compared
$0
Broker fees: paid by the lender
5.0
From 360+ Google reviews
House plans and architectural drawings spread across a table
The lender works from your plans and contract before it approves the build.Photo: Marina Zvada / Unsplash

Key Facts About Construction Loans in Australia

  • Minimum deposit

    Often 5% for a new build with a licensed builder and a fixed-price contract. A 20% deposit avoids Lenders Mortgage Insurance (LMI).

    LMI calculator
  • Interest during construction

    You pay interest only on the drawn-down balance, not the full approved loan amount. That keeps holding costs down while you may also be paying rent.

  • Interest rates

    Standard builds with licensed builders are priced much like standard home loans. Acreage, duplex and owner builder projects usually cost more, with fewer lenders.

  • Fixed-price building contract required

    Most lenders want a fixed-price contract from a licensed builder before they approve. It gives the lender certainty over the final loan amount and build timeline.

  • Build timeline

    Lenders set a time limit to finish the build from the first drawdown, and a window to make that first drawdown after approval. We check both against your builder.

  • First home buyers

    From 1 October 2025, eligible first home buyers can use the 5% Deposit Scheme for new builds, avoiding LMI with as little as a 5% deposit.

    5% Deposit Scheme

The detail behind these facts

Minimum deposit: Most lenders require a minimum 5% deposit for standard house-and-land packages and new builds with a licensed builder and fixed-price contract. A 20% deposit avoids Lenders Mortgage Insurance (LMI). From 1 October 2025, eligible first home buyers can access the Australian Government's 5% Deposit Scheme for construction and new builds, avoiding LMI with as little as a 5% deposit.

Interest during construction: You pay interest only on the drawn-down balance, not the full approved loan amount. This reduces your holding costs significantly while the build is underway, particularly helpful if you're also paying rent during construction.

Interest rates: Standard house-and-land packages with licensed builders and fixed-price contracts attract rates comparable to standard home loans. Acreage, duplex or dual occupancy builds may attract a small rate premium due to reduced lender competition. Owner-builder projects are considerably more expensive, with higher rates and significantly fewer lender options. We do not quote rates on this page: the rate you are offered depends on your build, your deposit and the lender.

Fixed-price building contract required: Most lenders require a fixed-price contract from a licensed builder before approving a construction loan. This gives the lender certainty over the final loan amount and build timeline.

Build timeline: Lenders commonly allow around 12 months from the first drawdown for construction to be completed, and you generally need to access your first drawdown within a set period after loan approval. Each lender sets its own limits, so we confirm them before you apply.

How the money moves

Construction loan progress payments explained

A progress payment is a drawdown of funds from your construction loan, released to your builder at each completed build stage. Your builder's contract sets the amount for each stage, and the lender pays the builder directly once the stage is done.

Timber frame of a new house going up, with scaffolding against a blue sky
Frame stage: one of five points where your builder claims a progress payment.Photo: Troy Mortier / Unsplash

How Does a Construction Loan Work?

The 5 standard progress payment stages: Most Australian construction loans are structured around five standard drawdown stages. At each stage, your builder submits a progress claim, you authorise the drawdown, and the lender releases the funds directly to your builder.

  1. Stage 1

    Slab (Base)

    The concrete foundation is laid and initial plumbing is roughed in.

    Before the lender pays

    This first claim may include the builder's initial deposit. Your builder submits a progress claim, you authorise the drawdown, and the lender pays the builder directly.

  2. Stage 2

    Frame

    External wall frames go up, brickwork begins, and roofing, plumbing and electrical rough-ins are installed.

    Before the lender pays

    Some lenders send a valuer or inspector to confirm the frame is complete before they release the funds.

  3. Stage 3

    Lock-Up

    Remaining windows, external doors and roofing are completed so the home can be secured.

    Before the lender pays

    The builder claims, you sign the authority, and the lender pays once it is satisfied the stage is done.

  4. Stage 4

    Fix-Out (Fit-Out)

    Lights, power points, plumbing fixtures, cabinetry and internal doors are installed.

    Before the lender pays

    Check the work against your contract before you sign the drawdown authority. Variations you asked for are usually paid from your own funds first.

  5. Stage 5

    Completion (Practical Completion)

    Final finishes, including fencing, site cleanup, painting and any contracted landscaping.

    Before the lender pays

    The final drawdown is released on practical completion and the issue of an occupation certificate. Then the loan converts to a standard home loan.

Interest is charged on what has been paid out Drawn so far Approved, not yet drawn

Illustration only. Each stage adds to the balance you pay interest on; the full loan only applies once the last stage is paid. Your builder's contract sets the amount for each stage.

At completion, the construction loan automatically converts to a standard home loan (variable or fixed), and normal principal and interest repayments commence. Your lender may request a progress inspection at each stage before releasing funds.

Vineeth Joseph

3 years ago on Google

Google

Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.

Vineeth Joseph

Google3 years ago on Google

Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.

Map my progress payments

Free, no obligation. Bring your builder's payment schedule.

Want the long version with common mistakes? Read how a construction loan works, step by step.

Types

Types of Construction Loans We Arrange

We work across every build type and borrower situation. Here's what we help with.

  • Drafting house plans with a pencil and scale ruler

    Photo: Daniel McCullough / Unsplash

    Standard House Build Loans (New Builds)

    A new home on a vacant block, with a licensed builder and a fixed-price contract. The most common construction loan, and the one lenders like best.

    How it works

    Building a new home on a vacant block (whether you've already purchased the land separately or are buying land and building simultaneously) is the most common construction loan scenario. Lenders are most accommodating for these builds because the risk profile is straightforward: licensed builder, fixed-price contract, standard residential construction in a well-serviced area. We match you to the right lender based on your deposit, income type, the land location and your builder's registration. For builds in Sydney's northwest growth corridors (Box Hill, Marsden Park, Schofields, Rouse Hill), we have strong experience placing borrowers with lenders who understand these markets.

  • Land and Construction Loans

    The land purchase and the build in one structure. The land settles first, then the build draws down stage by stage.

    How it works

    A land and construction loan combines the land purchase and the build into a single loan structure. The land component settles first (which is when your first loan repayments commence), and the construction loan then draws down progressively as each build stage is completed. Getting the structure right from the start matters here. We ensure the lender's policy supports your land settlement timeline and builder commencement date, so there's no gap between land settlement and build start that leaves you paying full principal and interest before construction has begun. Buying a package from a builder? See home and land package loans.

  • Knock-Down Rebuild Loans

    Demolish the house you own and build again. The land you already own does a lot of the work as security.

    How it works

    If you own an existing property and want to demolish and rebuild, a knock-down rebuild loan uses the equity in your land as security for the construction loan. Because you already own the land, the loan structure is often simpler; you're borrowing only for the construction costs, against a security (the land and finished home) that lenders assess conservatively. Lenders need to see council demolition approval, a licensed builder and a fixed-price building contract. We work through the pre-application checks with you before approaching lenders, so there are no surprises once the process starts. Pricing a rebuild? Read what a knockdown rebuild costs in Sydney.

  • First Home Buyer Construction Loans

    Building your first home can bring the First Home Owner Grant, the 5% Deposit Scheme and a stamp duty break on the land.

    How it works

    First home buyers building a new home have access to the same government support schemes available for property purchases, and in some cases more: NSW First Home Owner Grant (FHOG), $10,000 tax-free for eligible builds (house and land combined cost must not exceed $750,000). 5% Deposit Scheme (Home Guarantee Scheme): from 1 October 2025, eligible first home buyers can build with as little as a 5% deposit while avoiding LMI, with no income caps and no limit on scheme places (Sydney cap $1,500,000 for combined land and construction value). NSW Stamp Duty Exemption (FHBAS): full stamp duty exemption on land valued up to $350,000, concessional rate for $350,001 to $450,000. We confirm your eligibility for all applicable grants and schemes before you begin.

  • Investment Property Construction Loans

    Building to rent out. Stricter servicing, but interest only on drawn funds keeps holding costs down until a tenant moves in.

    How it works

    Building an investment property attracts higher interest rates and stricter serviceability assessment than owner-occupier construction loans. Lenders assess rental income projections (usually at an 80% rental shading factor), your existing debt position and your total portfolio exposure. For investors, the construction period can work in your favour from a cash flow perspective: interest-only on drawn funds during the build means lower holding costs before the property is tenanted. We structure investment construction loans to balance current cash flow with future borrowing capacity. More on investment property loans.

  • Owner Builder Loans

    You manage the build yourself. Fewer lenders, a bigger deposit and more paperwork: we tell you upfront if it will work.

    How it works

    Building a home yourself (without engaging a licensed builder as principal contractor) is significantly more complex from a lending perspective. Owner-builder projects are treated as high-risk by most lenders: most major banks do not offer owner-builder loans, and those that do require a maximum LVR of 60% (40% deposit minimum), proven construction experience and extensive documentation. We work with a small panel of specialist lenders who assess owner-builder applications. We're direct with you about what's required so you don't waste time on an application that won't succeed. What owner builder lenders ask for.

  • Duplex and Dual Occupancy Construction Loans

    Two dwellings on one title. Council approval, an experienced builder and the right lender policy make or break these.

    How it works

    Building two dwellings on a single title (whether side-by-side or main house and secondary dwelling) is achievable through residential construction loans for up to four dwellings. Lenders for duplex builds require council approval for dual occupancy, detailed construction plans and a builder with demonstrated experience in multi-dwelling residential construction. Some lenders offer competitive rates for dual occupancy builds, including up to 90% LVR for certain scenarios. Lender selection matters significantly here; this is exactly where a broker with specialist lender access makes a real difference. Adding a granny flat instead? See how to finance a granny flat build.

Find the right construction loan

Not sure which type you are? Sumit will tell you in one call back.

Sound familiar?

Common construction loan situations we solve

Most people come to us with one of these. Here is what usually gets in the way, and what we do about it.

  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824
  • Knocking down and rebuilding

    The challenge: You own the house and the land, but you need demolition approval, a builder and a loan that covers the build while you live elsewhere.

    How we handle it

    We work out how much of your land equity counts, check the lender’s demolition and contract rules first, and time the loan so you are not paying for longer than you need to.

  • Land settles before the builder starts

    The challenge: Your block settles months before construction begins, so repayments start before you have a home to live in.

    How we handle it

    We pick a lender whose build start rules match your builder’s timeline and set up the land and the build as one plan, not two separate loans.

  • Renting while you build

    The challenge: You are paying rent and the new loan at the same time, and you want to know what each stage will cost you month by month.

    How we handle it

    We map the interest-only repayments stage by stage against your rent, so you can see the tightest month before you sign the building contract.

  • The quote went up after approval

    The challenge: Variations or a revised contract price mean the build now costs more than the loan you were approved for.

    How we handle it

    We check what the lender will accept, whether a higher approval is possible, and how much of the gap should come from savings or a contingency.

  • Self-employed and building

    The challenge: Your income is real but harder to show on payslips, and construction lenders are already strict.

    How we handle it

    We go to lenders whose policy accepts your tax returns, BAS or accountant’s letter, and prepare the file so the build and the income are assessed together.

  • Building your first home

    The challenge: Grants, the 5% Deposit Scheme and stamp duty on the land all have their own rules, and the build adds a contract and a timeline.

    How we handle it

    We check every scheme you qualify for, then line up the grant, the deposit and the loan so the money is there when the builder needs it.

Sumit · 1:35
What banks look at before they lendSumit Joshi, RyRo Loan Centre · income, debts and savings: what lenders check firstWatch with transcript

These are common situations, not client stories. Every loan depends on your circumstances and the lender's policy. Self-employed? See self-employed and low doc home loans.

The process

How the Construction Loan Process Works

From initial strategy call to final drawdown, here's how we manage the process for you. 6 steps from first call to completion.

  1. Step 1

    Strategy Call and Pre-Qualification

    We start with a conversation about what you're building, where, with which builder (or whether you're still selecting one), and your financial position (income, deposit, existing debts). We identify the right loan structure and lender shortlist before any application is lodged.

  2. Step 2

    Pre-Approval

    We prepare and lodge your pre-approval with the most suitable lender. For construction loans, this involves assessing your income and financial position in the same way as a standard home loan, but without the building contract (which comes later). Pre-approval gives you a confirmed borrowing limit so you can finalise your land purchase, select a builder and sign a building contract with confidence.

  3. Step 3

    Full Approval: Building Contract and Plans

    Once your fixed-price building contract is signed, we lodge the full application. The lender assesses the building contract, plans and specifications, confirms the final loan amount, and may commission a construction valuation (an "as if complete" valuation). Approval time depends on the lender and how complete the application is.

  4. Step 4

    Land Settlement (Land and Construction Loans)

    For land and construction packages, land settlement occurs first. Your loan repayments begin at this point on the land component. We coordinate with your conveyancer to ensure settlement proceeds on time and the construction drawdown schedule is ready to activate when building commences.

  5. Step 5

    Progress Drawdowns During Construction

    At each build stage, your builder submits a progress claim. We walk you through what's needed for each drawdown request (typically a signed progress claim, an invoice from your builder and confirmation that the stage is complete). Some lenders require an independent progress inspection before releasing funds. We manage communication with the lender throughout the build to keep drawdowns moving without delays.

  6. Step 6

    Final Drawdown and Loan Conversion

    At practical completion, the final drawdown is released to your builder and the loan converts from a construction loan to a standard home loan. We review the converted loan rate and structure, and reach out if refinancing or restructuring makes sense once the build is done and you've established your equity position.

What lenders ask to see

  • Income evidencePayslips, or tax returns and BAS if you are self-employed
  • Bank statements and IDPlus details of any existing debts
  • Signed fixed-price building contractFrom a licensed builder
  • Council-approved plans and specificationsDA or CDC approval for the build
  • Builder's licence detailsLenders check the registration
  • Home Building Compensation insuranceArranged by your builder in NSW
Start with a strategy call

Step 1 is a free strategy call. No obligation.

Sumit · 0:54
We guide you every step until settlementSumit Joshi, RyRo Loan Centre · Sumit on staying with you until the last paymentWatch with transcript

Deposit & costs

How Much Deposit Do You Need for a Construction Loan?

Deposit requirements for construction loans in Australia depend on your build type, your borrower profile and which lender you're working with.

Typical construction loan deposits by build type
Build typeTypical depositWhat to know
Standard house-and-land and new buildsFrom 5%Licensed builder, fixed-price contract. Above 80% LVR triggers LMI; 20% avoids it
First home buyers using the 5% Deposit Scheme5%No LMI, no income caps, no limit on scheme places
Duplex and dual occupancy buildsOften 10% to 20%Some lenders go to 90% LVR for standard dual occupancy
Acreage and rural buildsOften 20%+Lenders are more conservative, with less competition
Owner-builderOften 40%Maximum 60% LVR at most lenders who accept them

Deposit detail by build type

Standard house-and-land and new builds (licensed builder, fixed-price contract): Minimum 5% deposit. Borrowing above 80% LVR triggers LMI. A 20% deposit (80% LVR) avoids LMI and accesses the most competitive rates and broadest lender choice.

First home buyers using the 5% Deposit Scheme: From 1 October 2025, eligible first home buyers can build with a 5% deposit with no LMI, no income caps and no limit on scheme places. The government guarantees up to 15% of the loan value through participating lenders.

Duplex and dual occupancy builds: Typically 10% to 20% deposit. Some lenders allow up to 90% LVR for standard dual occupancy scenarios.

Acreage and rural builds: Lenders are more conservative here. Most require 20%+ deposit with reduced lender competition compared to suburban builds.

Owner-builder: Minimum 40% deposit (maximum 60% LVR) at most lenders who accept owner-builder projects.

Sumit · 0:47
Four tips for the best chance of approvalSumit Joshi, RyRo Loan Centre · a bigger deposit means less LMIWatch with transcript

Other Costs to Budget For

  • Builder deposit

    Builders typically ask for a deposit of around 5% of the contract price before they start. It is separate from your home loan deposit.

  • Land stamp duty

    Transfer duty is payable on land in NSW within 3 months of signing. First home buyers may pay none on land up to $350,000, and a concession to $450,000.

    Stamp duty calculator
  • Council approvals and permits

    Development Application (DA) or Complying Development Certificate (CDC) fees, depending on your council and build type.

  • Construction insurance

    Lenders want Home Building Compensation (formerly Home Warranty Insurance) in place before construction starts. Your builder generally arranges it under NSW law.

  • Valuation fees

    An "as if complete" valuation at approval, and sometimes progress inspections at each stage. We confirm the lender's valuation requirements upfront.

  • Contingency

    Cost overruns are common. We generally recommend a 5% to 10% reserve in savings, as the loan usually cannot be increased mid-build.

More on these costs

Builder deposit: Builders typically require a deposit of approximately 5% of the construction contract price before commencement. This is separate from your home loan deposit.

Land stamp duty: Transfer duty is payable on land purchase in NSW and must be paid within 3 months of signing the land contract. First home buyers building on land valued up to $350,000 may qualify for a full stamp duty exemption under the First Home Buyers Assistance Scheme, with a concessional rate on land from $350,001 to $450,000. See the NSW first home buyer stamp duty concession.

Construction insurance: Most lenders require Home Building Compensation (formerly Home Warranty Insurance) to be in place before construction commences. Your builder is generally responsible for arranging this under NSW law.

Valuation fees: Construction loans may require multiple valuations during the build: an initial "as if complete" valuation at approval, and sometimes progress inspections at each stage.

Contingency: Cost overruns are common in construction. We generally recommend maintaining a 5% to 10% contingency reserve in savings, as construction loans cannot typically be increased mid-build if your contract cost exceeds the approved amount.

Owner builder

Owner builder loans: what lenders ask for

An owner builder loan funds a home you build yourself, without a licensed builder as principal contractor. It can be done, but fewer lenders offer it, and the ones that do want proof you can finish the job on budget.

  • A larger depositLenders that accept owner builders usually cap the loan at a lower LVR than a standard build
  • Your owner builder permitIssued in NSW for owner builder work over the threshold set by NSW Fair Trading
  • Detailed costings and trade quotesSo the lender can see the whole build is funded
  • Council-approved plansThe same plans and approvals as any other build
  • Evidence you can manage the projectConstruction experience helps a lot
  • A buffer for overrunsThere is no fixed-price contract to cap the cost
Check my owner builder project

Free, no obligation. Tell us about your project.

Aerial view of curving suburban streets lined with new family homes
Buying the block first? The land loan and the build loan need to fit together.Photo: Shanjir H / Unsplash

Buying land first

Land loans in Sydney & NSW

Whether you're buying a vacant block to build on, land in a new estate, or rural or lifestyle property, the right land loan structure and lender can make the difference between a smooth settlement and a last-minute scramble. We compare 50+ lenders for residential, rural and commercial land across Sydney and NSW, and guide you on deposits, registration timing and build conditions so you know what to expect before you make an offer.

The full guide is on our land loans page. Buying a package from one builder? See house and land package loans.

What is a land loan?

A land loan (vacant land loan) is finance for purchasing land only, with no dwelling. It suits buyers of residential blocks to build on, house-and-land packages where land settles first, rural or lifestyle blocks, and investment or development land. Lenders treat land differently to established homes: deposit requirements, LVRs and approval criteria vary by land type and location.

You borrow a set amount, repay with interest over an agreed term, and the land is security for the loan. Deposit requirements typically range from 20% to 40% depending on whether the land is registered, serviced, and in a mainstream or rural location. We match you to lenders whose policy fits your block type, build timeline and location so you get a clear path to approval.

Registered land and building after you buy

Most lenders only lend on registered land: subdivided, serviced and on title. Unregistered lots in new estates often require you to pay a deposit to the developer first; the loan and settlement happen once the land is registered. We help you plan for that timing and avoid surprises with build or registration deadlines.

Some lenders require construction to start within a set period; others allow land banking. If you're buying land now and building later, we find a lender whose build timeframe matches your plans so you're not forced to start before you're ready.

Land in Sydney and growth corridors often demands a larger deposit than an established home, because lenders see land as higher risk. We compare options across our panel so you see realistic deposit requirements and terms for your suburb and block type. First home buyers may be able to combine a land loan with government schemes; we check eligibility as part of your strategy. Use our loan repayment calculator to estimate repayments for your loan amount and term.

Why a broker

Why Use a Construction Loan Broker in Sydney?

Construction loans are more complex than standard home loans; there are more documents, more stages, more lender-specific policies to work through, and more things that can go wrong if the application isn't prepared correctly. Not every lender handles construction loans well.

  • Slow drawdowns

    Some lenders have slow drawdown processes that frustrate builders and delay your build.
  • Policies that do not fit

    Some have policies that don't suit your builder's contract structure, land location or build type.
  • Valuations that fall short

    Some value the finished home conservatively, which can reduce the amount they approve.

How we pick the lender for your build

We know which lenders on our panel of 50+ are fastest and most builder-friendly for standard Sydney builds, which ones have the most favourable policies for dual occupancy, knock-down rebuild and acreage projects, and which ones move efficiently through the drawdown process so your builder isn't waiting on funds.

Working with a specialist construction loan broker in Sydney (one who has dealt with builds across the Hills District, northwest Sydney, southwest Sydney and beyond) means your application is prepared correctly the first time, with the right lender, and the drawdown process is managed so your build stays on schedule.

Match my build to a lender

Free, no obligation.

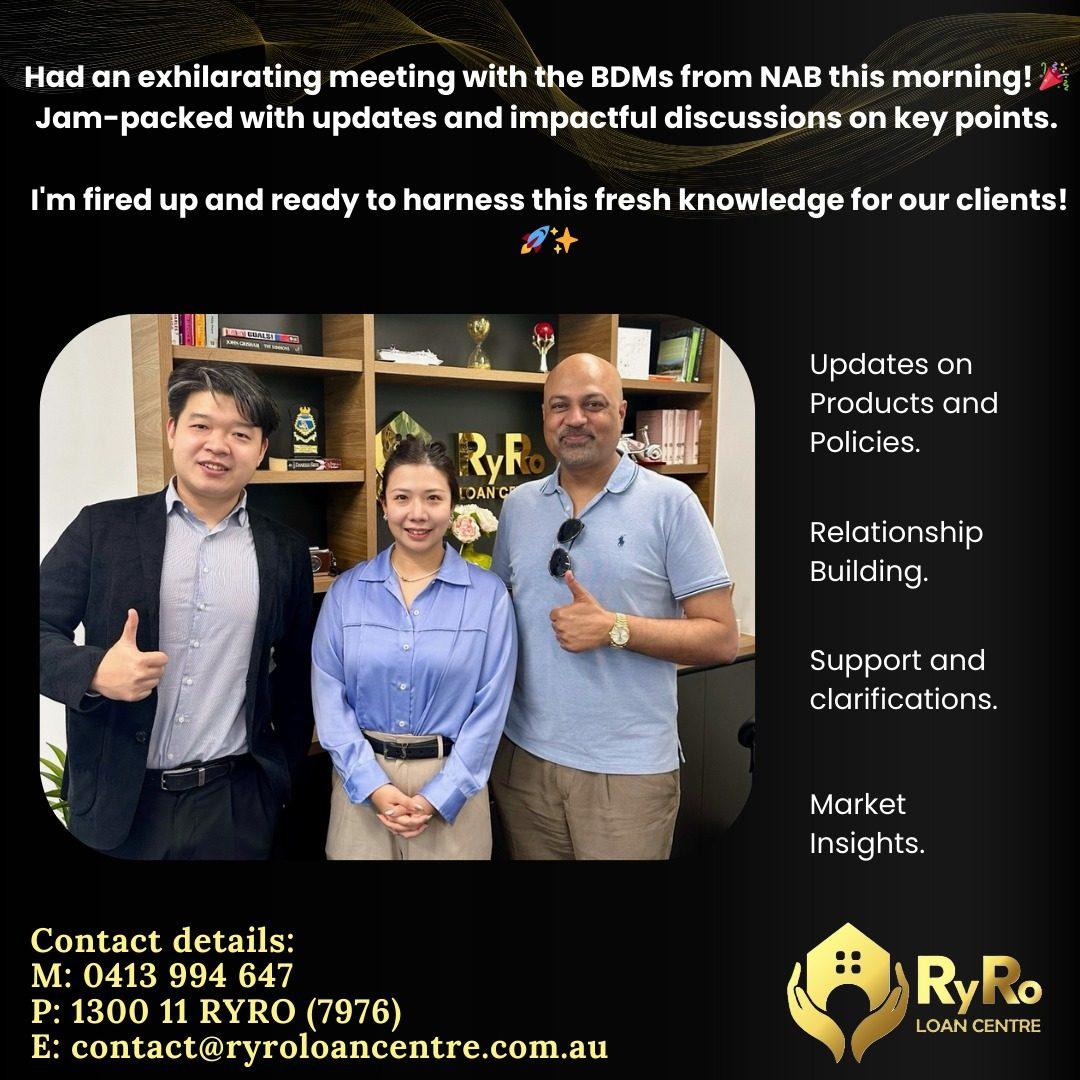
Sumit Joshi meeting NAB business development managers at the RyRo office
Sumit meeting NAB business development managers at the Norwest office.
  • Google5.0 from 360+ Google reviews
  • 2,500+ clients helped
  • Credit Rep 446824

Why RyRo

Why Choose RyRo Loan Centre for Your Construction Loan?

  • Access to 50+ Lenders Including Construction Specialists

    Construction loans need lenders with strong construction policies: fast drawdowns, fair valuations, flexible build timelines. We match your build type to the lender who will serve it best.

  • $0 Broker Fees

    Our service is completely free. We're paid a commission by the lender when your loan settles. Advice, lender comparison, application, drawdowns and post-settlement review, at no direct cost to you.

  • We Manage the Drawdowns

    Each progress drawdown needs paperwork, your builder and the lender. We manage this at every stage so you're not chasing your bank while also managing a build.

  • Local Sydney and Hills District Knowledge

    We're based in Norwest and know Sydney's growth corridors, builders and council approvals, from Box Hill and Marsden Park in the northwest to Austral and Leppington in the southwest.

    Kellyville mortgage broker
  • One Process from Land to Completion

    Buying land, moving from a land loan into construction, or building on a block you own: we manage the whole finance journey from pre-approval to final drawdown and loan conversion.

  • What Our Clients Say

    5.0 out of 5 from 360+ verified Google reviews. More than 2,500 Australians have trusted RyRo Loan Centre with their lending.

    Read all 360+ Google reviews

Our construction loan clients highlight the same things in their reviews: we make a complex process manageable, we communicate clearly at every stage, and we don't disappear after approval. Live near our office? Meet us as your Castle Hill mortgage broker or across the Hills District.

Google reviews

What Our Customers Say

Real Google reviews of RyRo Loan Centre, word for word. The first two are from clients who built their home with us.

Google

5.0

From 360+ Google reviews

Sumit · 2:56
Approved in days after her broker went quietSumit Joshi, RyRo Loan CentreWatch with transcript
Read all 360+ Google reviews
  • Jaimie Sarwary

    11 months ago on Google

    Google

    I truly cannot express how amazing our experience has been with RyRo Loan Centre. Sumit and his team have gone above and beyond to make my mine and my husband’s dream of building our first home come true. They have been in constant communication throughout the process, explained everything in detail and have taken the stress away from finding a home loan. We had a very tight deadline and they made it work, even exceeded our expectations by having us approved for a much higher amount than an alternate broker advised. Sumit, we are forever grateful for your service, you have been an absolute pleasure to deal with!

    Jaimie Sarwary

    Google11 months ago on Google

    I truly cannot express how amazing our experience has been with RyRo Loan Centre. Sumit and his team have gone above and beyond to make my mine and my husband’s dream of building our first home come true. They have been in constant communication throughout the process, explained everything in detail and have taken the stress away from finding a home loan. We had a very tight deadline and they made it work, even exceeded our expectations by having us approved for a much higher amount than an alternate broker advised. Sumit, we are forever grateful for your service, you have been an absolute pleasure to deal with!

  • Vineeth Joseph

    3 years ago on Google

    Google

    Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.
    Vineeth Joseph

    Google3 years ago on Google

    Around five years ago, we were introduced to Sumit when we initially contemplated constructing a house. Sumit provided us with valuable financial guidance regarding the essential steps to initiate the house-build. Over the years, he has been a constant source of support, assisting us not only throughout the construction of our home but also during the challenging times of the COVID-19 pandemic. More recently, he helped us in refinancing our home loan. He has always offered pragmatic and honest recommendations that prioritise our best interests. Sumit greatly simplified the financial aspect, taking the time to explain the nuances involved in dealing with financial institutions. Sumit and his team have always been approachable and have promptly responded to our queries and requirements.
  • chris sukumar

    5 months ago on Google

    Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

    chris sukumar

    Google5 months ago on Google

    Sumit at Ryroloan Centre made our first home possible Five stars for Sumit Joshi at Ryroloan Centre. As first home buyers we had no idea where to start. Sumit was easy to contact from day one. He picked up calls, replied to texts fast, and explained everything in simple terms. He secured us a really good rate that beat what our bank offered. The whole pre-approval and settlement process was smooth because he stayed on top of every document and deadline. I want to thank Dean and whole team thank you all. Couldn’t recommend Sumit more highly if you’re a first home buyer.

  • Karra Le

    5 months ago on Google

    Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

    Karra Le

    Google5 months ago on Google

    For someone like us who's completely new to the home loan process and first home buyers, they're very responsive and answered all the questions we have. Sumit, Dean and Meet helped us get through the process and supported us all the way till the end. Their team is very knowledgeable and professional. Highly recommended!

Start my construction loan

Free, no obligation.

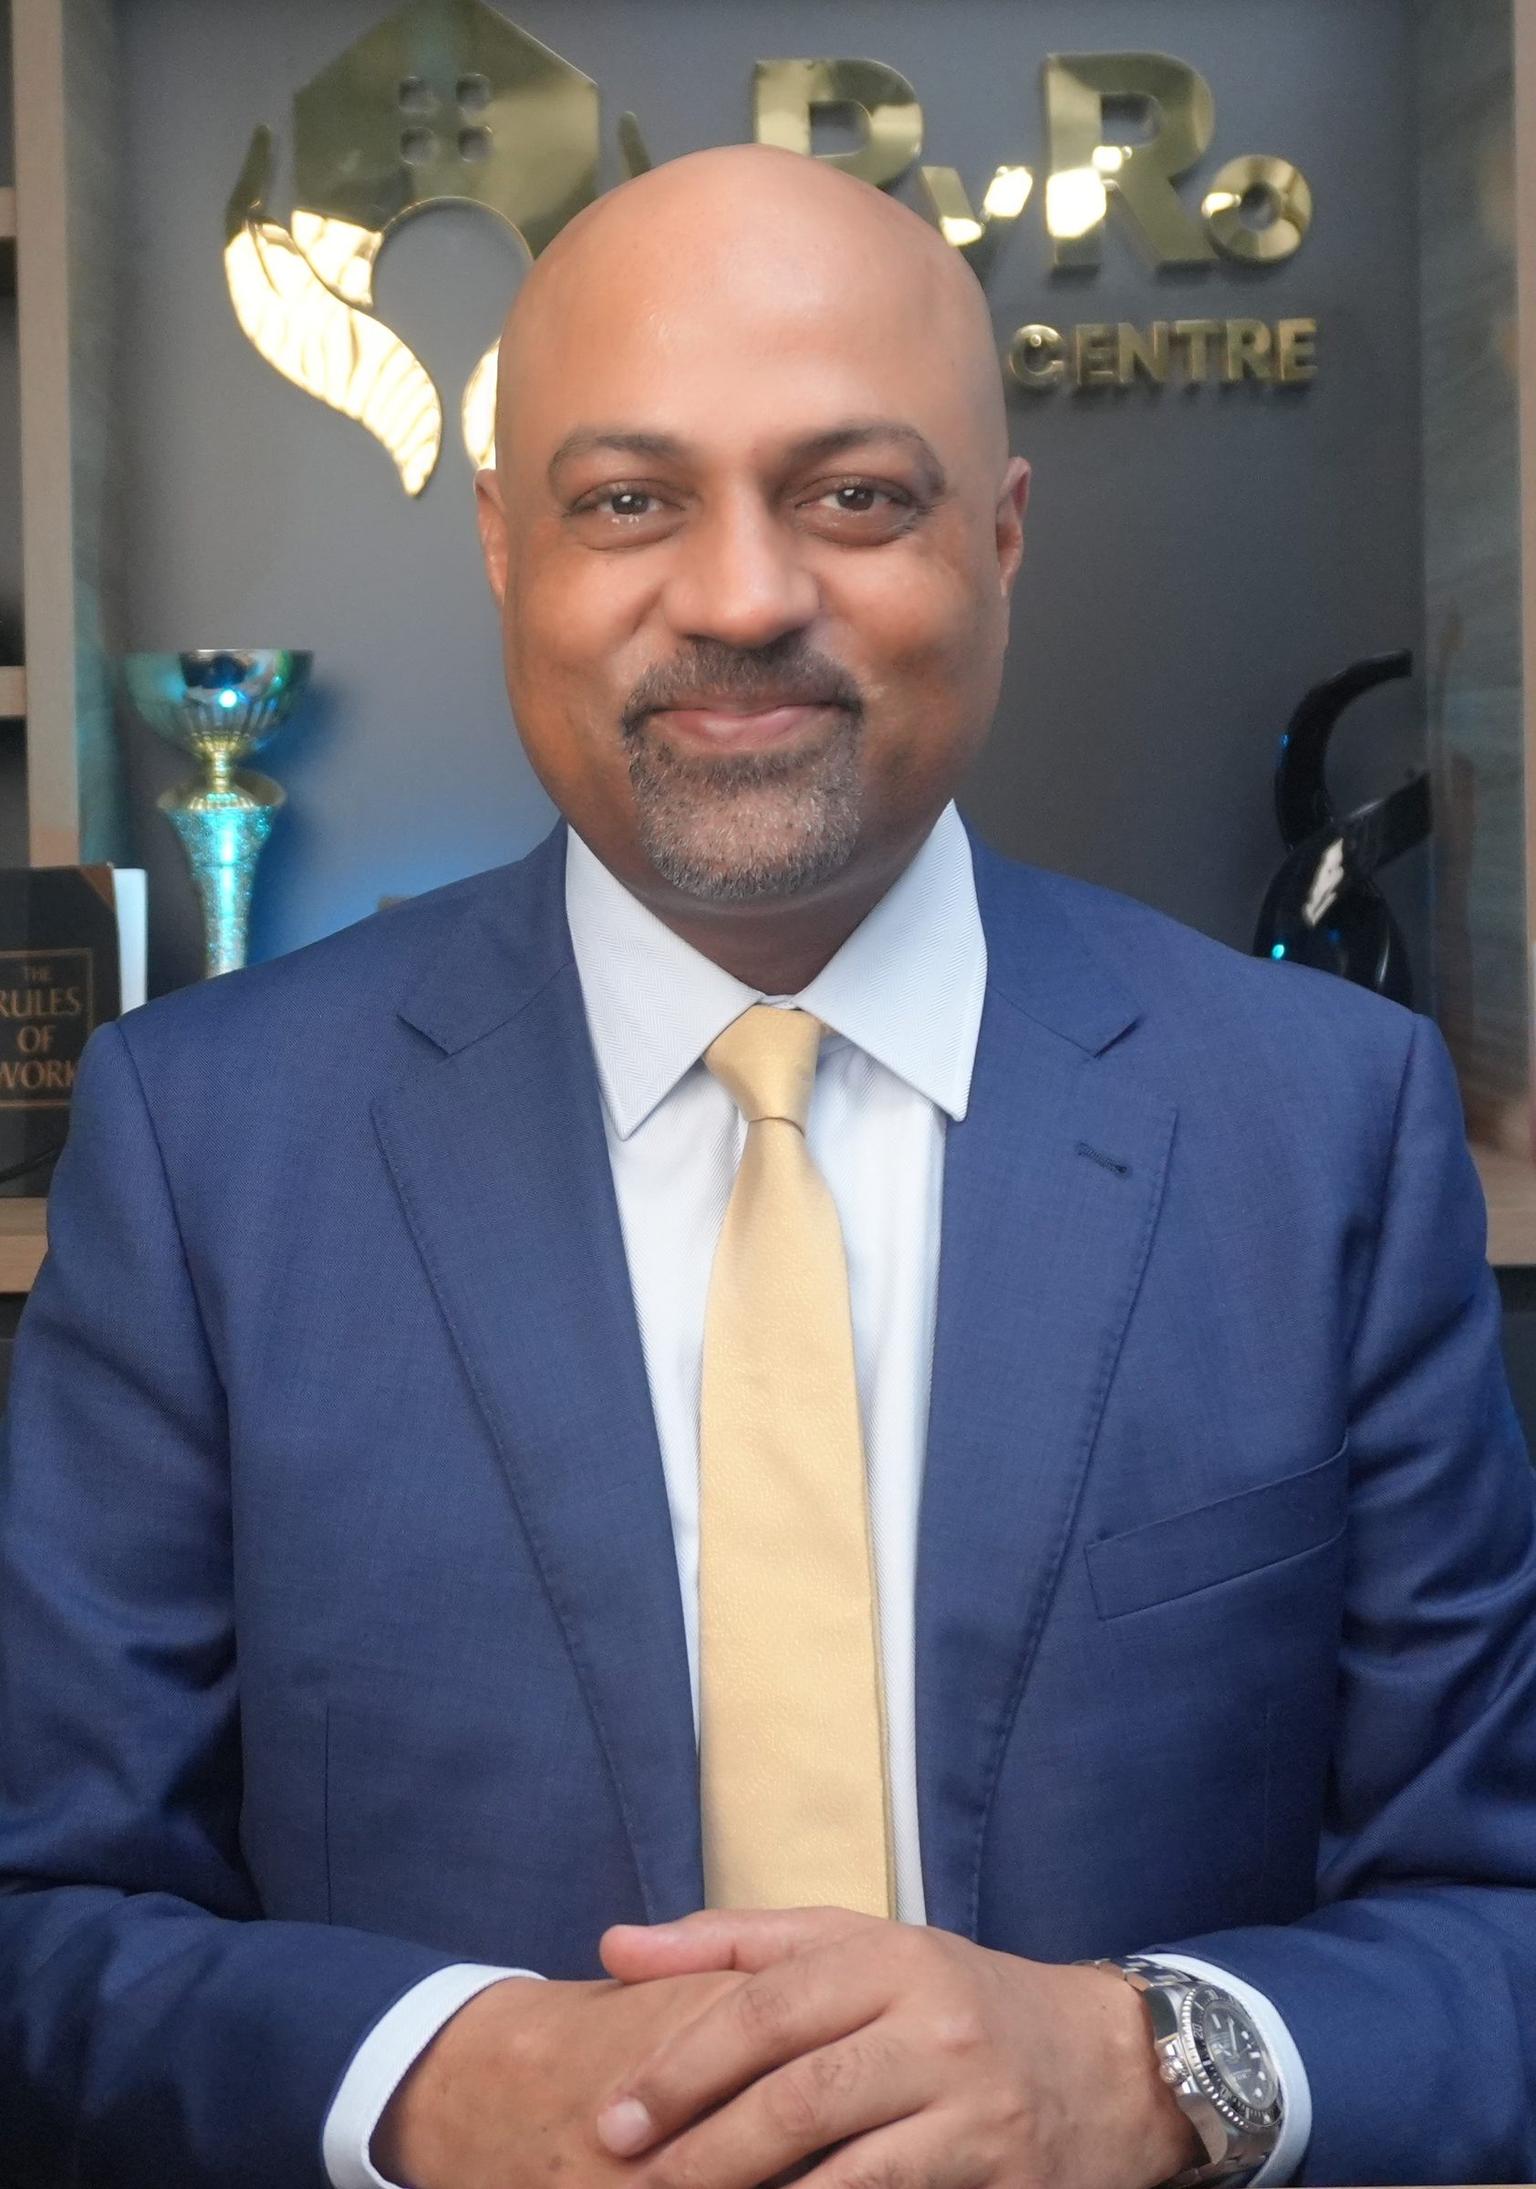
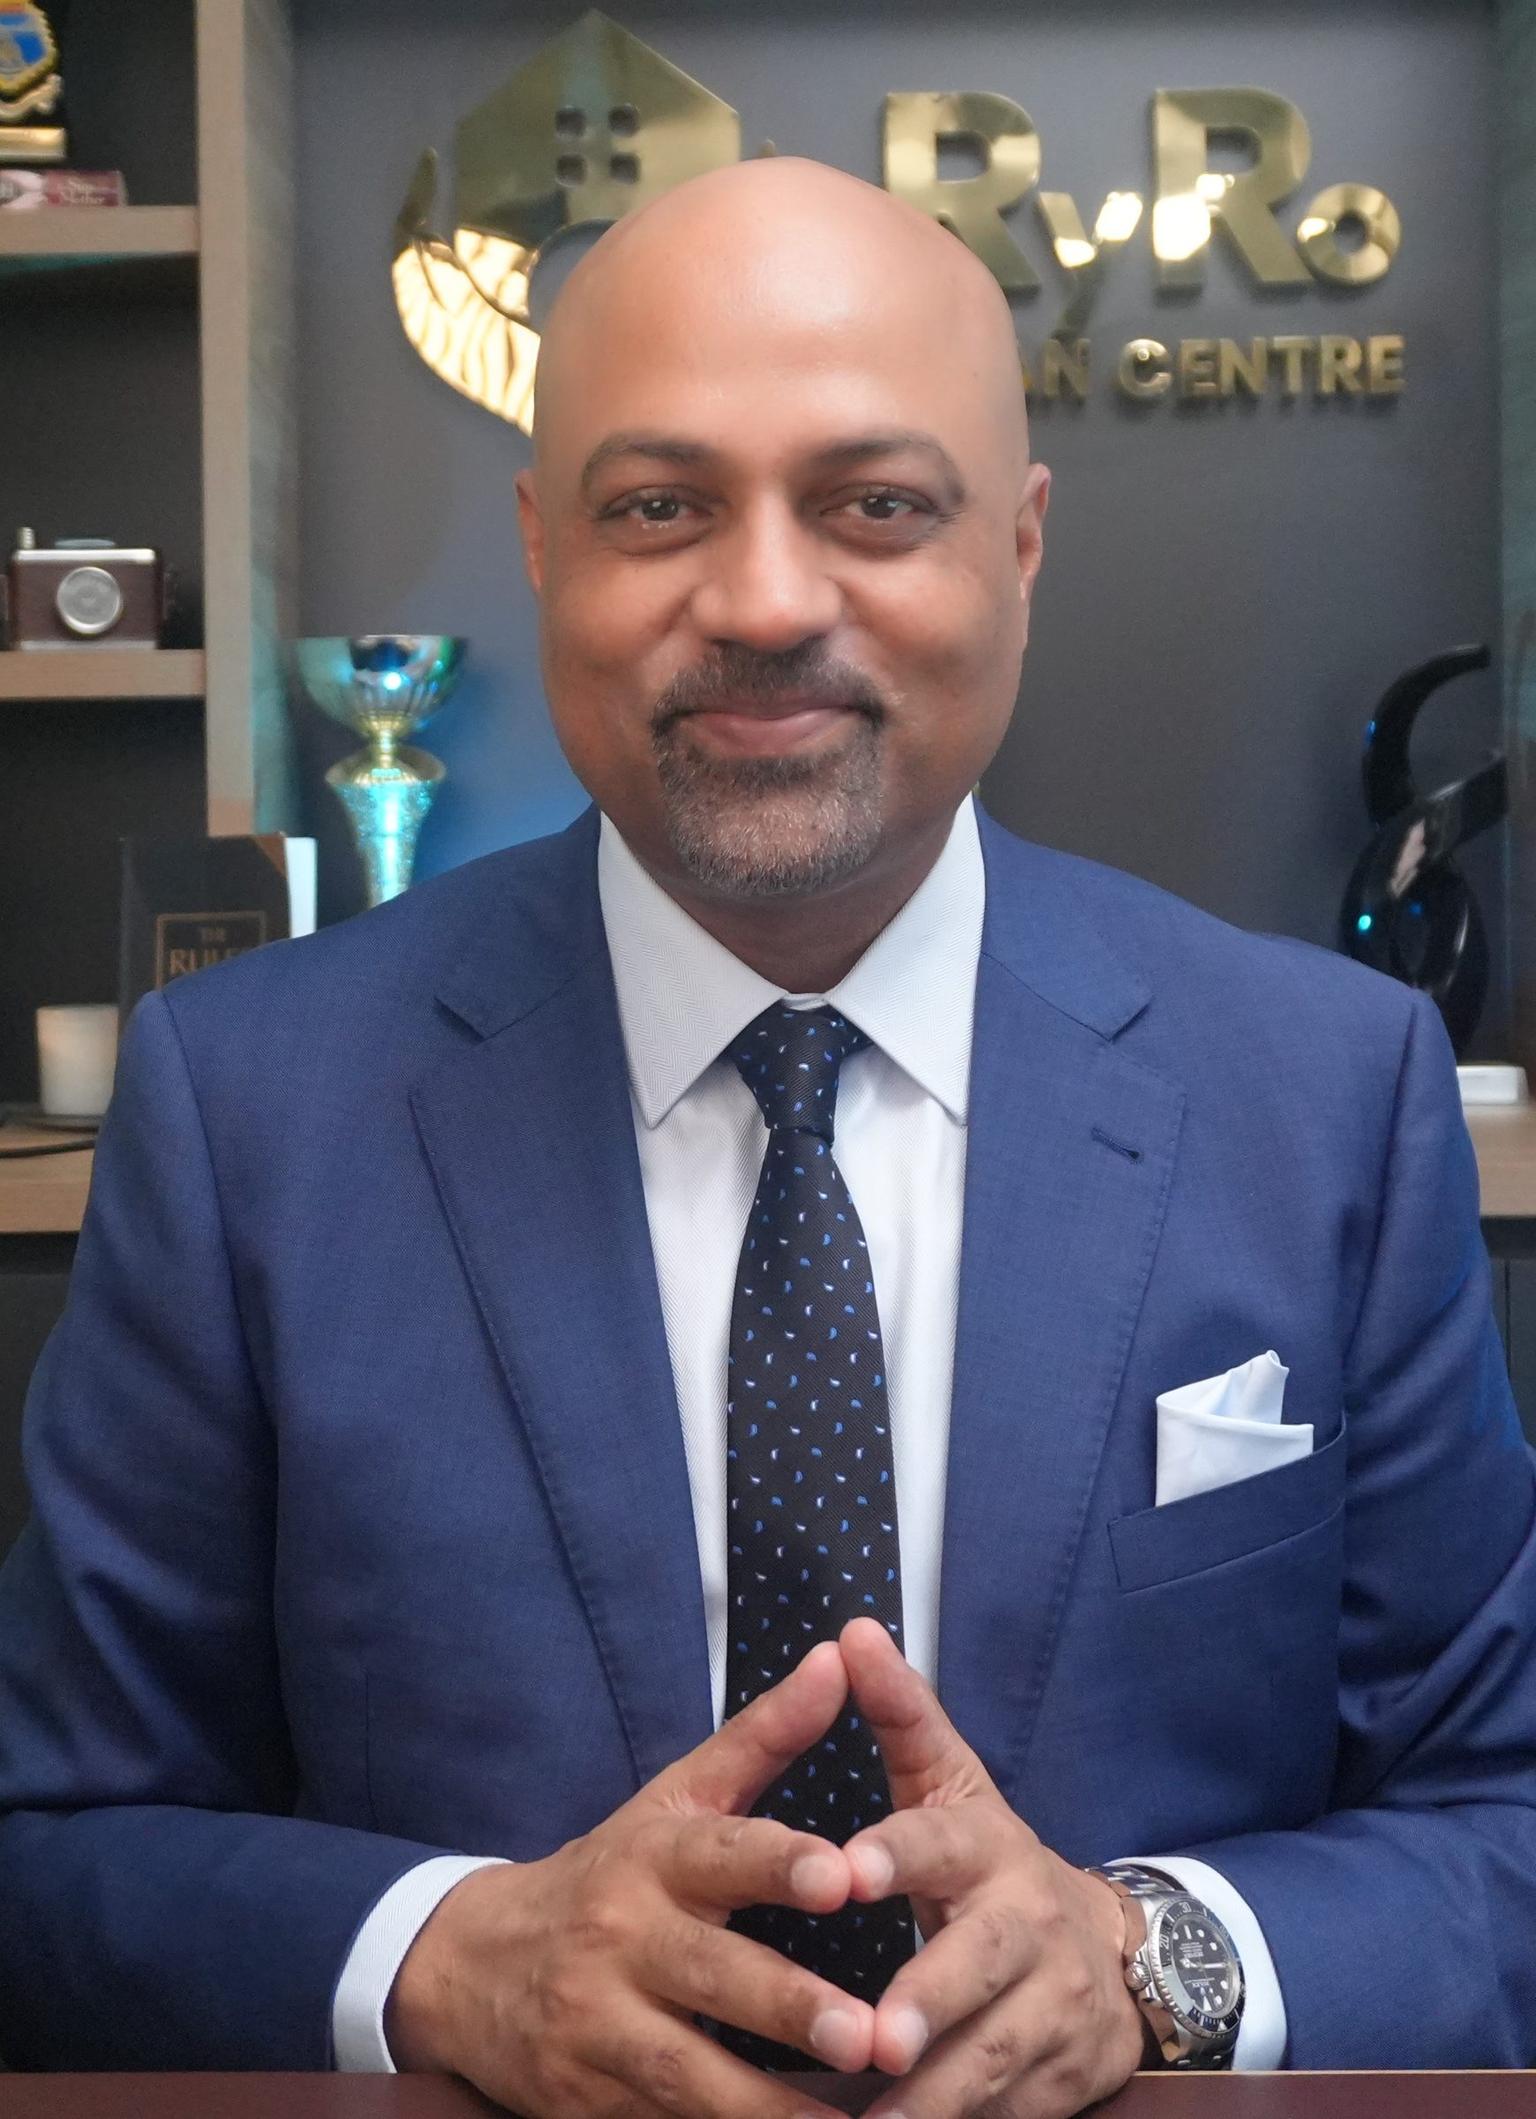
Sumit Joshi, principal mortgage broker at RyRo Loan Centre, in a blue suit at the Norwest office

Sumit Joshi JP

Principal broker, Credit Rep 446824

Who you will deal with

The RyRo Team

“Construction finance has more moving parts than a standard home loan. Tell us what you're building and we'll find the right lender for your situation from day one.”

Our team helps buyers across Sydney and Australia secure the right construction loan. We compare 50+ lenders and guide you from strategy to settlement, then through every progress payment until the keys are yours.

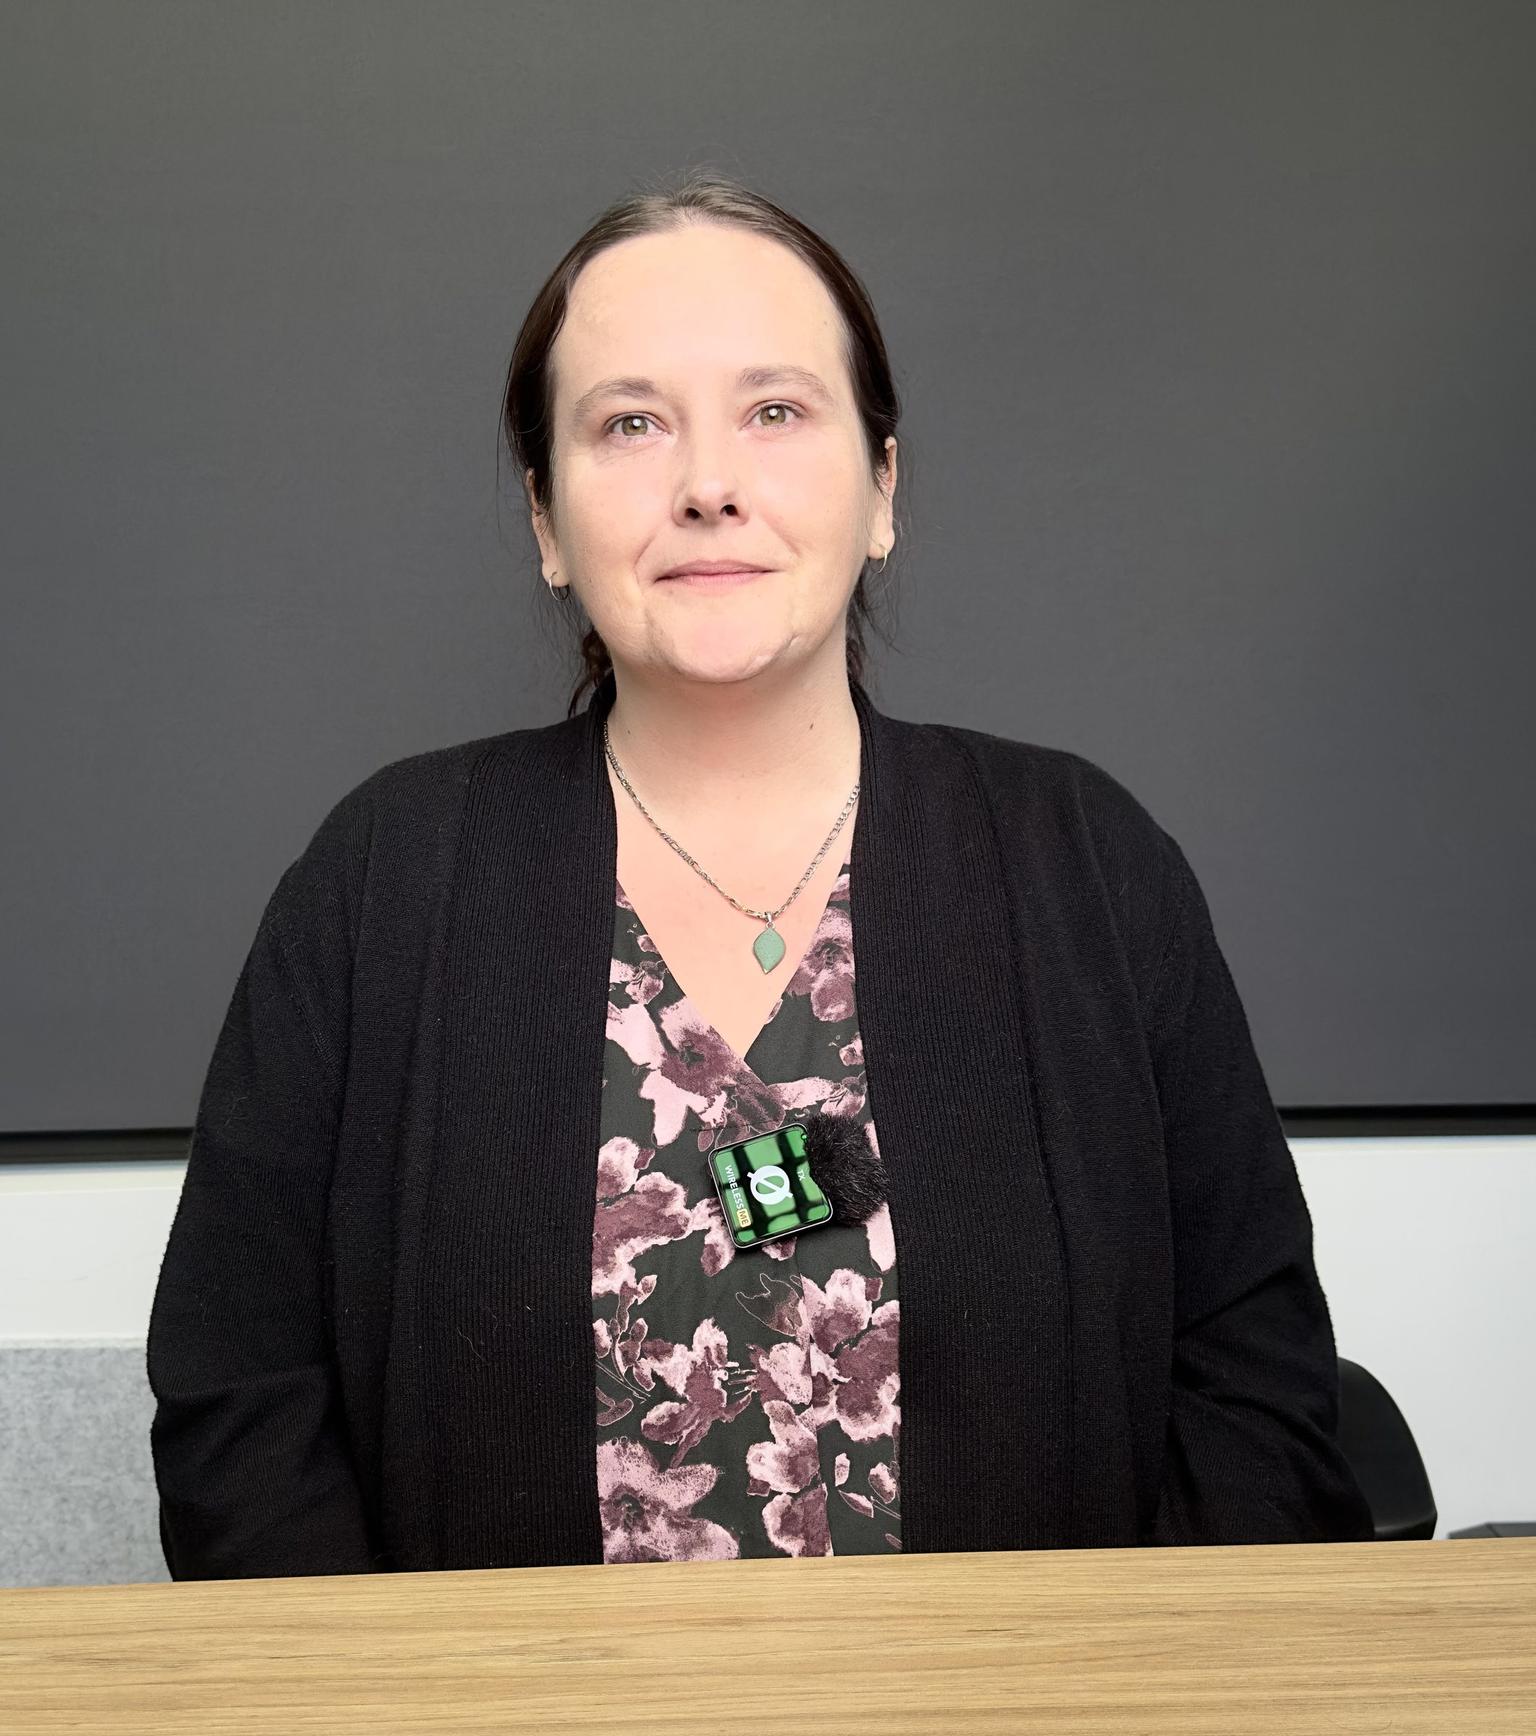
Kathryn Thomas, loan processor at RyRo Loan Centre

Loan processor

Kathryn Thomas

Kathryn looks after settlements and client updates, so someone is always chasing the lender and telling you where your loan is at.

Sumit Joshi, 2020 Broker of the Year
  • AFG Broker Assurance Recognition 2024 badge
  • AFG Excellence Awards finalist 2025 badge
  • MFAA 10 year member badge
Talk to Sumit about my build

Sumit reads your details and calls you back.

From the blog

Building and renovating guides from the RyRo blog

Read these before you sign a build contract: how progress draws actually work, what a knockdown rebuild costs in Sydney right now, and when refinancing beats a separate renovation loan.

Free PDF · 2 pages
Photo: Marina Zvada / Unsplash

Free 2-page guide

Land + Build Cost and Progress-Draw Planner

How the money flows from vacant block to finished home: the land loan, the construction stages and the contract traps to check before you commit.

  • The progress-draw schedule, stage by stage
  • A land holding cost worksheet
  • What a fixed-price contract must include

Google5.0 from 360+ Google reviews · Emailed to you straight away

FAQs

Frequently Asked Questions: Construction Loans

Have a question not covered here? View all FAQs or ask us directly.

Most common questions

What is a construction loan and how is it different from a regular home loan?

+
A construction loan is designed specifically for building a new home. Instead of advancing the full loan amount upfront, it releases funds in stages (called progress payments) as each phase of construction is completed. You pay interest only on the amount drawn down at any point, not the full approved balance. Once construction is complete, the loan converts to a standard home loan with principal and interest repayments. A regular home loan advances the full amount at settlement and isn't structured to accommodate staged building payments.

How much deposit do I need for a construction loan in Australia?

+
For a standard new build with a licensed builder and fixed-price contract, most lenders require a minimum 5% deposit. Borrowing above 80% LVR triggers Lenders Mortgage Insurance (LMI). A 20% deposit avoids LMI entirely. From 1 October 2025, eligible first home buyers can build with a 5% deposit using the expanded Home Guarantee Scheme, avoiding LMI without needing a 20% deposit. Owner-builder projects typically require a minimum 40% deposit due to their higher risk profile.

What is a construction loan broker?

+
A construction loan broker is a mortgage broker who specialises in arranging finance for new home builds, including house-and-land packages, knock-down rebuilds, dual occupancy and major renovations. At RyRo Loan Centre, we compare construction loan options from 50+ lenders, prepare your application, manage the drawdown process at each build stage, and handle the loan conversion at completion, at no cost to you.

Can I get a construction loan as a first home buyer?

+
Yes. First home buyers can access construction loans on the same basis as standard home loans, and may also be eligible for additional support: the $10,000 NSW First Home Owner Grant (for builds where the combined land and construction cost is under $750,000), stamp duty exemptions on land under $350,000, and the expanded 5% Deposit Scheme (from 1 October 2025, no income caps, no place limits, $1,500,000 price cap for Sydney). We confirm your eligibility for all applicable grants and schemes before you apply.

How do construction loan progress payments work?

+
A progress payment is a drawdown of funds from your construction loan, released to your builder at each completed build stage. The standard stages are: slab, frame, lock-up, fix-out and completion. At each stage, your builder submits a progress claim, you authorise the drawdown, and the lender releases the funds, sometimes after commissioning a progress inspection to confirm the stage is complete. You pay interest only on the amounts drawn down, not the full loan balance.

Build types & process

Can I use a construction loan for a knock-down rebuild?

+
Yes. Knock-down rebuild loans use the equity in your existing land as security. The loan covers the construction cost of the new dwelling, and the land remains as security throughout. You'll need council demolition approval, a licensed builder and a fixed-price building contract. Some lenders also require a demolition certificate before releasing construction funds. We manage the pre-application checks and lender matching for knock-down rebuild projects.

Do construction loans have higher interest rates than home loans?

+
For standard residential builds with a licensed builder and fixed-price contract, construction loan rates are comparable to standard home loan variable rates. Some lenders apply a small rate loading during the construction period only, which reverts to the standard rate at completion. More complex builds (dual occupancy, acreage, owner-builder) may attract a higher rate due to the additional risk and fewer available lenders. We compare rates across our full panel for your specific build type.

What documents do I need to apply for a construction loan?

+
For the initial pre-approval, documentation is similar to a standard home loan: income verification (payslips, tax returns or BAS statements for self-employed borrowers), bank statements, existing debt details and identification. For full approval, you'll also need a signed fixed-price building contract, council-approved building plans, a licensed builder's registration details and evidence of Home Building Compensation insurance. We manage the document checklist and application preparation from start to finish.

How long does construction loan approval take?

+
Pre-approval for a construction loan typically takes 1 to 5 business days for standard applications. Full approval (including the building contract assessment and construction valuation) typically takes 5 to 15 business days depending on the lender and complexity of the build. More complex builds (dual occupancy, acreage, owner-builder) take longer. We set realistic timeframes at the start and manage lender communication throughout to keep your application progressing.

Can I get a construction loan for a duplex or dual occupancy?

+
Yes. Residential construction loans are available for up to four dwellings on a single title. Dual occupancy and duplex builds require council approval (not all councils or zoning areas permit dual occupancy), detailed construction plans, a builder with proven multi-dwelling experience, and a lender with appropriate dual occupancy lending policies. Some lenders offer competitive rates for these builds at up to 90% LVR. Lender selection is critical for dual occupancy; we match you to lenders whose policies genuinely suit your project.

Interest, deposit & after the build

Do I pay interest on the full amount during the build?

+
No. During construction you pay interest only on the money the lender has paid out to your builder so far, not on the full approved loan. Your repayments start small after the first progress payment and grow as each stage is paid. Most lenders set the build period up as interest only, then switch the loan to principal and interest once the home is finished. Ask us to map the repayments for your build so you can plan for rent or a current mortgage at the same time.

Can I use my land as the deposit for a construction loan?

+
Often, yes. If you already own the block, the equity in it can count toward the deposit for the build, so you may not need much cash on top. Lenders value the land and the finished home together and lend against that combined value. How much equity counts depends on the lender, the land value and what you still owe on it. We check this before you sign a building contract, so you know how much of your savings you need to keep for costs and a buffer.

How long does a construction loan last?

+
A construction loan has two phases. The build phase runs while your builder is working and the lender pays each stage; lenders set a time limit for this, so check it against your builder's timeline. Once the home is finished and the last payment is made, the loan becomes a standard home loan for the rest of the term, often 30 years. We confirm the lender's build period and what happens if the build runs late before you apply.

Can I refinance after the build is finished?

+
Yes. Once the home is complete and the loan has converted to a standard home loan, you can refinance like any other borrower. A finished home is often worth more than the land and contract price combined, which can improve your loan to value ratio and your choice of lenders. Check for break costs if any part of the loan is fixed. We review your loan after completion and tell you plainly whether a switch is worth it.

Do I need a fixed-price building contract?

+
For most lenders, yes. A fixed-price contract with a licensed builder tells the lender what the build will cost and what it is lending against. Cost-plus contracts, where the final price can move, are harder to finance and fewer lenders accept them. Your contract, plans and the builder's licence and insurance details are part of the full approval. If you are still choosing a builder, get pre-approval first so you know your budget before you sign.

Can I get a construction loan as an owner builder?

+
Yes, but fewer lenders offer owner builder loans and they ask for more. Expect a larger deposit than a standard build, your owner builder permit, detailed costings and quotes from trades, and evidence you can manage the project. Many major banks do not lend to owner builders at all, so the lender choice matters more here than on any other build type. We tell you upfront whether your project is likely to be approved before you spend money on an application.

Talk to Sumit

Ready to Finance Your Build?

Construction loans have more moving parts than a standard home loan. Get a broker in your corner from day one: one who knows the lenders, manages the drawdowns and keeps the process on track.
Sumit Joshi, principal broker at RyRo Loan Centre

Start My Construction Loan

We'll call you to discuss your build and the right finance structure for your situation.

Free, no obligation. We generally respond within an hour.

Google5.0360+ Google reviews

We generally respond within an hour. Prefer to pick a time? Book your strategy call online or contact us.

Sumit Joshi of RyRo Loan Centre smiling in a blue suit and gold tie

Sumit Joshi JP

Principal broker, Credit Rep 446824

  • Sumit reads your details and calls you back
  • No obligation and no credit check
  • Free for home loans: the lender pays us
Sumit · 2:59
From two properties to four in six monthsSumit Joshi, RyRo Loan CentreWatch with transcript

More videos from Sumit

From 360+ Google reviews
5.0
Clients helped
2,500+
Broker fees on home loans
$0
Progress payments we manage with your lender
5
“Sumit is an outstanding mortgage broker. He patiently worked through our application and got us an awesome result when many other brokers wouldn't assist as we are small business owners. Thank you!”
Belinda White · Google review

Sumit Joshi JP, Credit Rep 446824. AFG Award Winner 2013 to 2019 and AFG Excellence Awards finalist 2022 to 2026.

Get my free loan review